

Guides
September 19, 202610 min read
COBRA Paying for Rehab After Job Loss
Employer coverage can go inactive in the insurer’s system weeks before a continuation election posts.
Rize OCRead
Same-day assessments · Orange County, CA
Rize OC
Editorial Team

If you're weighing insurance deductible reset starting treatment, the short answer is that you shouldn't hold off on care just to catch a new plan year. Waiting can save money on paper, but only if your plan resets on a date you can name and your symptoms are stable enough to wait. We'll walk through how to check both, so the decision rests on your actual plan and not a guess.
A deductible is the amount you pay for covered services before your plan starts sharing the cost, and the reset is the date that amount goes back to zero. For outpatient mental health or addiction care, that date changes what your first weeks of treatment cost. Our deductible overview is a good plain definition if you want the formal wording from the source.
Here's the practical picture. Say you start a program in November. You may pay toward your deductible for those weeks, then watch it return to zero in January and begin paying again. Start in January instead, and you pay toward one deductible for the whole stretch. That's the entire logic of timing, and it only helps if the numbers on your own plan actually work that way.
Two figures decide how much the reset matters to you. The first is how much of your deductible you've already met this year. If you've met most of it, starting now is often the cheaper choice, because your plan is already paying a larger share. The second is your out-of-pocket maximum, the yearly cap on what you pay for covered care. Once you hit it, covered services cost you nothing more until the reset, which makes a late-year start look very different from an early-year one.
Benefits vary by plan, and coverage depends on medical necessity, so a general rule can't tell you your number. At Rize OC, our team verifies your benefits before care starts, so you'll see your deductible status and likely costs before you commit to a date.
Most employer plans run on the calendar year, but plenty don't. Some companies set the plan year to start on July 1 or October 1, often tied to when the company renewed its contract with the insurer. If your benefits enrolled mid-year, your reset date may follow the employer's schedule and not the calendar at all. Your insurance card won't say, so check your Summary of Benefits and Coverage or the member portal, where the plan year dates are usually printed near the top.
Marketplace plans and most individual plans you buy yourself generally follow the calendar year. If you changed plans partway through the year because of a job change or a qualifying life event, though, you likely started over with a new deductible on the day the new plan began. That can work in your favor if you're looking at a start date in the fall, since a brand-new deductible hasn't been met yet and the reset won't change much.
A few plan features also behave differently from the standard deductible:
Ask your insurer or our admissions team which of these apply to you. When you call, have your member ID and the name of the plan holder ready, and we'll confirm your plan year dates while we verify your benefits. It takes the guesswork out of picking a start date, and you'll hear the answer in plain terms before you decide anything.
Outpatient programs bill by the day or the session, so the reset shows up as a change in who pays what on each claim, not as one large bill. Before your deductible is met, the plan often applies the allowed amount for each service to your deductible, and you're responsible for that amount. After it's met, you typically pay coinsurance or a copay, and the plan covers the rest.
Take a program that runs from December into February. In December, your claims may go toward a deductible you've mostly met, so your share could be small. When the plan year turns over, the first claims in January can land back at the full deductible. People are often surprised by that jump, even though the care hasn't changed at all.
Coinsurance is the piece that gets overlooked. A plan that covers 80 percent after the deductible still leaves you 20 percent of every claim until you reach your out-of-pocket maximum. The coinsurance definition shows how that split works, and you can compare it against your plan's out-of-pocket maximum to see where your yearly spending stops.
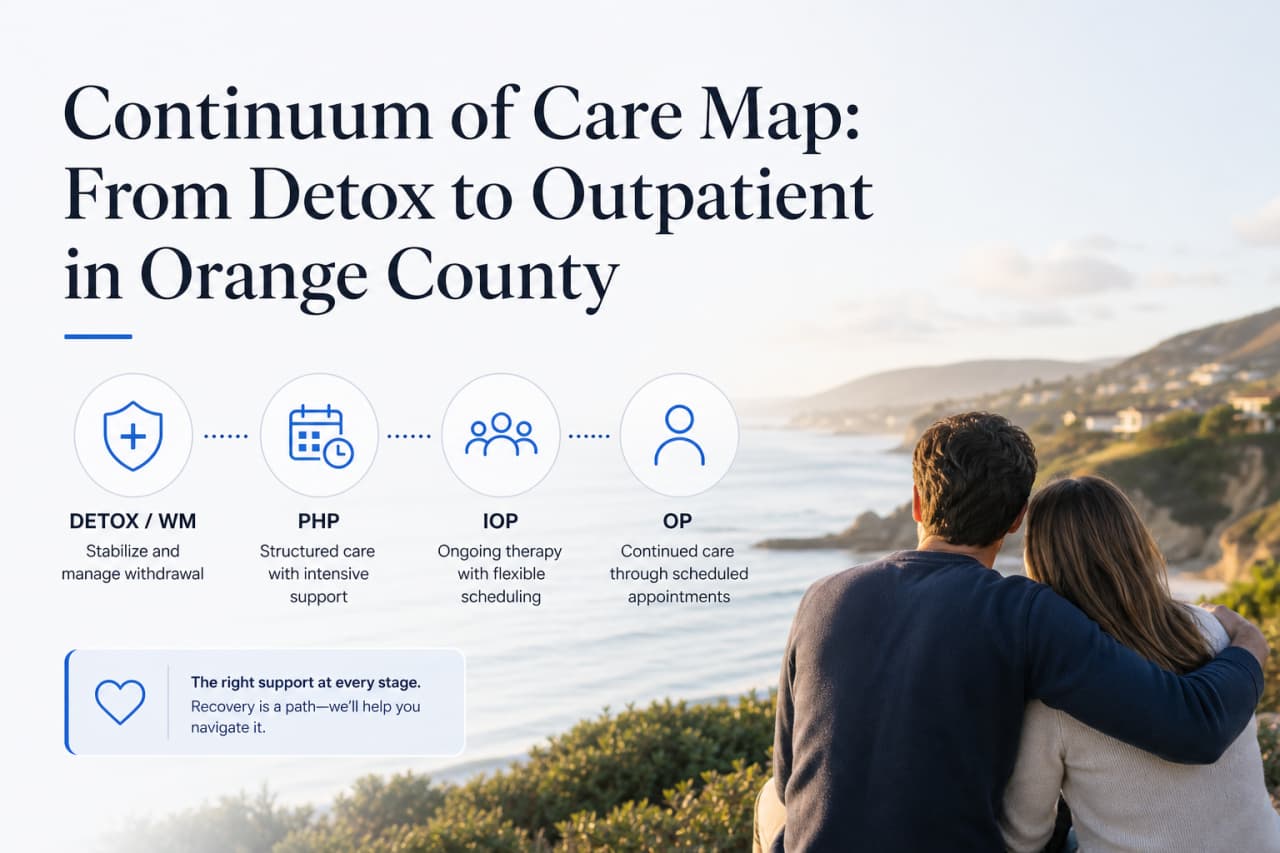
Higher levels of outpatient care can also cost differently from lower ones. A partial hospitalization program has more days of service per week than standard outpatient, so you'd reach your deductible and your maximum faster. Ask whether your plan sets separate cost sharing for each level.
When our team verifies your benefits, we look at where you are on your deductible and out-of-pocket maximum so you can see the likely cost of each month before you pick a start date.
Start with the question that can change your whole plan: are your symptoms stable enough to wait? If you're using alcohol or drugs daily and could face withdrawal, or if you're having thoughts of harming yourself, a reset date shouldn't factor in at all. Call 988 or 911 if you're in danger, and ask a clinician about the safest level of care first.
If waiting is safe, run these checks in order:
Our admissions team can run most of this with you at once. Call (949) 461-2620 with your member ID, and we'll verify your benefits and tell you where you stand before you choose a date. Because a licensed clinical team recommends the level of care after an assessment, you'll also know which program, PHP, IOP or standard outpatient, the numbers apply to.
If your insurer's answers don't match what you were told earlier, ask for the representative's name and a reference number for the call. Those details help if you ever need to dispute a claim later.
If your program starts in November and runs into February, expect two sets of numbers, not one. Claims are processed by the date of service, so December visits count against the old year and January visits count against the new one. Your out-of-pocket maximum also starts over, which means a cost you stopped paying in December can come back in the first weeks of the new year.
Ask the insurer whether any prior authorization has to be renewed when the plan year changes. Some approvals are tied to a date range, and a gap between approvals can delay a claim. Also ask whether the plan changes at renewal, since employers sometimes switch carriers or adjust cost sharing on January 1. Your benefits can look different in the new year even if the reset date is the same.
Waiting for the reset only makes sense when a few things line up. Your symptoms are stable, the reset is close, and you've met little of this year's deductible. If you've already met most of it, delaying usually costs you the cheaper weeks. Treatment that is postponed also isn't free, because symptoms and daily stress don't pause for a billing calendar.
If you do wait, use the time for things that don't depend on the date. Collect your plan year dates, confirm your network status, and have a benefits check done so a start date is ready when you are. Our team can run that check now and again closer to the reset, and we'll tell you plainly if starting sooner looks like the better choice. If your situation changes while you wait, you can move your start date up at any time.
The call usually starts with a few basics. A member of our admissions team will ask for your name, date of birth, and the member ID and group number on your insurance card. If you're covered under someone else's plan, they'll also ask for the plan holder's name and birthdate. Having the card in front of you makes the call much shorter.
From there, we contact your insurer and check the details that affect your start date. That includes whether your plan covers outpatient mental health or addiction treatment, how much of your deductible you've met, where you stand on your out-of-pocket maximum, and whether the level of care you need requires prior authorization. We'll also tell you when your plan year turns over, so you can see how a November, December or January start would change what you pay.
We work with many commercial PPO plans, but we don't accept Medi-Cal or Medicaid. If your plan isn't one we can bill, you'll hear that on the first call, along with other options to consider, so you don't spend time planning around coverage that won't apply.
Coverage depends on your plan and on medical necessity, so the result is an estimate of your costs, not a final bill. We'll explain it in plain terms and answer questions about anything that's unclear. If you're not sure you're ready to enroll, you can still ask for the numbers first.
Some people also want a clinical conversation on the same call. A licensed clinical team recommends the level of care after an assessment, and we can start scheduling that when you're ready.
To check your benefits and compare start dates, call Rize OC at (949) 461-2620, or use the Contact Us button below.
About the Author
Helpful educational resources from Rize OC.
In This Article
Topics
Ready for Help?
Confidential support, same day.
Employer coverage can go inactive in the insurer’s system weeks before a continuation election posts.

Compare sliding scales, payment plans, insurance costs, and California public options before agreeing to treatment financing.

You'll be able to decide whether to run your intensive outpatient care through insurance or pay cash, and what to ask before you commit.
Take the Next Step
If you or a loved one is struggling with addiction or mental health, the Rize OC team is here to help — confidentially and with no obligation.