

Guides
August 19, 20269 min read
Insurance Deductible Reset: Planning Treatment Around Your Plan Year
You'll be able to decide whether to start treatment now or after your deductible resets.
Rize OCRead
Same-day assessments · Orange County, CA
Rize OC
Editorial Team

A benefits letter you can't quite read shouldn't be the reason you delay intensive outpatient care. Most people in Orange County can start on either insurance or cash pay, and the better route depends on your plan, your deductible, and who you want seeing your records. Here's how the two compare on cost, speed, and privacy, so you can choose with real numbers in hand.
The two routes differ in who decides what you get and how much you pay up front. With insurance, your plan sets the terms. It decides whether IOP is medically necessary, how many weeks it will approve, and what you owe through deductibles and copays. With cash pay, you and the program agree on a price, and no insurer reviews your treatment plan.
Insurance usually costs less out of pocket if your plan covers IOP, but coverage depends on the plan and on medical necessity. We work with many commercial PPO plans and verify your benefits before care starts, so you'll know what your plan says before you commit. We don't accept Medi-Cal or Medicaid, which matters if that's your current coverage. The state's Medi-Cal page explains how that program works.
Cash pay makes the most sense when your plan excludes outpatient mental health or addiction care, your deductible is high and unmet, or you want no insurer involvement at all. You take on the full cost, so ask for the exact figure in writing before you begin.
Three questions usually settle it:
Your plan's own summary of benefits is the quickest place to start, and HealthCare.gov explains the general rules on mental health and substance use coverage. If you'd rather have someone read your card and tell you what it means in plain terms, our admissions team at our Lake Forest location can do that on a short call.
Three things set the price of IOP more than anything else: how many sessions you attend each week, how many weeks your clinical team recommends, and whether you have other needs that add to the plan. Because the schedule depends on your assessment, nobody can quote a fair total before that assessment happens.
IOP is multi-session weekly care, and we offer two tracks, morning and evening, so it can fit around work, school, and family. Your track doesn't change the clinical content, but the number of weeks does change the total. Our clinical team recommends a level of care after an assessment that covers your medical and psychiatric history, withdrawal risk, living situation, and goals, and they adjust the plan as you progress. A plan that starts at IOP may step down to standard outpatient, which is lower frequency, or you may need to start at partial hospitalization instead.
If you have both a mental health condition and a substance use disorder, dual diagnosis care treats them together in one plan. Ask whether that's included in the quoted figure or billed separately, because the answer shapes your comparison.
Then there's the part that changes by payment route:
Before you compare, ask the program for a written breakdown rather than a single monthly number. You want to know the weekly cost, what's included, and what happens to the price if your clinical team recommends more or fewer weeks than first expected. Our admissions team can walk you through that and check your benefits at the same time, so you're comparing real figures instead of estimates.
Verification and prior authorization are two separate checks, and mixing them up is the most common reason people get surprised by a bill. Verification answers what your plan says it covers. Prior authorization answers whether the insurer agrees that IOP is medically necessary for you, and it's usually a yes or no on a specific number of weeks.
Here's the order things typically happen in, in five steps:
Step 1. You share your insurance card details with our admissions team, who check your benefits before care starts.
Step 2. They look at whether your plan covers intensive outpatient care, what your deductible and copay or coinsurance are, and whether approval is required in advance.
Step 3. Our clinical team completes your assessment, since the insurer will want to see the clinical reasons behind the level of care.
Step 4. If your plan requires prior authorization, the request goes to the insurer with that clinical information.
Step 5. The insurer approves a set period, and you'll usually be asked to share more clinical updates if you need additional weeks.
Keep in mind that a verified benefit isn't a promise of payment. Coverage depends on your plan and on medical necessity, and an approval can cover fewer weeks than your clinical team recommends. That's why we tell people what the plan says in plain terms before they commit, rather than after the first week.
Have your card ready, along with the name of the policyholder if it isn't you. If you can find your plan's phone number for behavioral health benefits, that helps too, because some plans route mental health and addiction claims through a separate department. Ask the insurer for a reference number on any call so you can point to it later if something gets disputed.
Paying through insurance means your diagnosis and treatment dates travel to the insurer, because a claim can't be processed without them. The insurer then holds those records, and its reviewers may ask for clinical notes to decide whether IOP is medically necessary. An explanation of benefits (EOB) is also usually mailed or posted online for the policyholder, so a spouse or parent who holds the plan can see that you received care, even if they can't see your session content.
Cash pay keeps that claim trail from existing at all. No insurer receives a diagnosis, and no EOB arrives at anyone's address. That matters most for people who share a plan with family or want their employer-sponsored coverage kept out of it. Your records still exist at the program, and they're handled as confidential health information either way. Cash pay changes who else receives them, not whether the program keeps them.
Some practical points before you decide:
Ask the insurer who receives the EOB and whether you can set a different mailing address or paperless delivery for it.
Ask the program what it shares with an insurer, and when, if you choose that route.
If you're a working professional, remember that your employer typically pays for the plan but doesn't receive your treatment details through ordinary claims. Our executive privacy focus exists because discretion is a frequent concern, so say so in your first call and we'll explain how we handle it.
You can also start on one route and reconsider. If you verify benefits and dislike what the paperwork would involve, tell our admissions team before care begins. Choosing cash pay at that point is a simple conversation, and it's much easier than trying to unwind a claim after it's been filed.
A denial letter is the start of a review process, and most plans give you a window of time to appeal, so read the date on it first. The letter should name the reason, such as a finding that IOP isn't medically necessary or that the service needs approval you didn't have. That reason tells you what to fix.
Call the insurer and ask for the denial reason in writing if the letter is vague. Then ask for the appeal deadline, the appeal address or portal, and a reference number for the call. Write down the name of everyone you speak with.
Next, bring in the program. Our clinical team can supply the assessment findings behind the recommended level of care, and our admissions team can tell you what the insurer asked for and what was sent. Insurers often reverse a decision when the clinical record answers the stated reason, though no one can promise how a particular review will turn out. If your plan offers an external review after an internal appeal, ask how to request it. HealthCare.gov is a good reference if you want to check your rights, but the letter itself will name the steps for your plan.
Don't pause treatment decisions while the appeal runs if your clinicians recommend care now. Ask admissions what cash pay would cost in the meantime and whether you can switch routes, and get any figure in writing before you agree.
If you're unsure where your denial leaves you, call our admissions team at (949) 461-2620 with the letter in hand. We'll read it with you, explain what it means in plain terms, and lay out your options.
Mixing routes is possible in some situations, but it depends on your plan and on how the program bills. Some people pay cash for weeks their insurer won't approve, or for services the plan excludes. Ask admissions whether that arrangement is available, and get the split in writing before you agree, so you know which weeks fall under which route.
You don't need either to call. Our admissions team can talk with you about what's going on, and a licensed clinical team completes the assessment that determines your level of care. If your plan requires a referral, the insurer's behavioral health line can tell you. Bring a list of current medications and any past treatment if you have one.
Our team verifies benefits before care starts, so you'll usually know what your plan says before your first session. If you're waiting on an answer and want to begin sooner, ask admissions whether cash pay is an option for the interim. Get any figure in writing, and ask whether switching routes later is allowed.
We don't accept Medi-Cal or Medicaid, so a plan like that can't be billed here. Your options are cash pay or a different commercial plan if you have one. If you're unsure which type of plan you hold, the name on your card or your plan's member line will tell you, and our admissions team can help you read it.
About the Author
Helpful educational resources from Rize OC.
In This Article
Topics
Ready for Help?
Confidential support, same day.
You'll be able to decide whether to start treatment now or after your deductible resets.
Compare PHP and IOP affordability using scheduled hours, likely duration, insurance steps, and household costs before choosing a program.
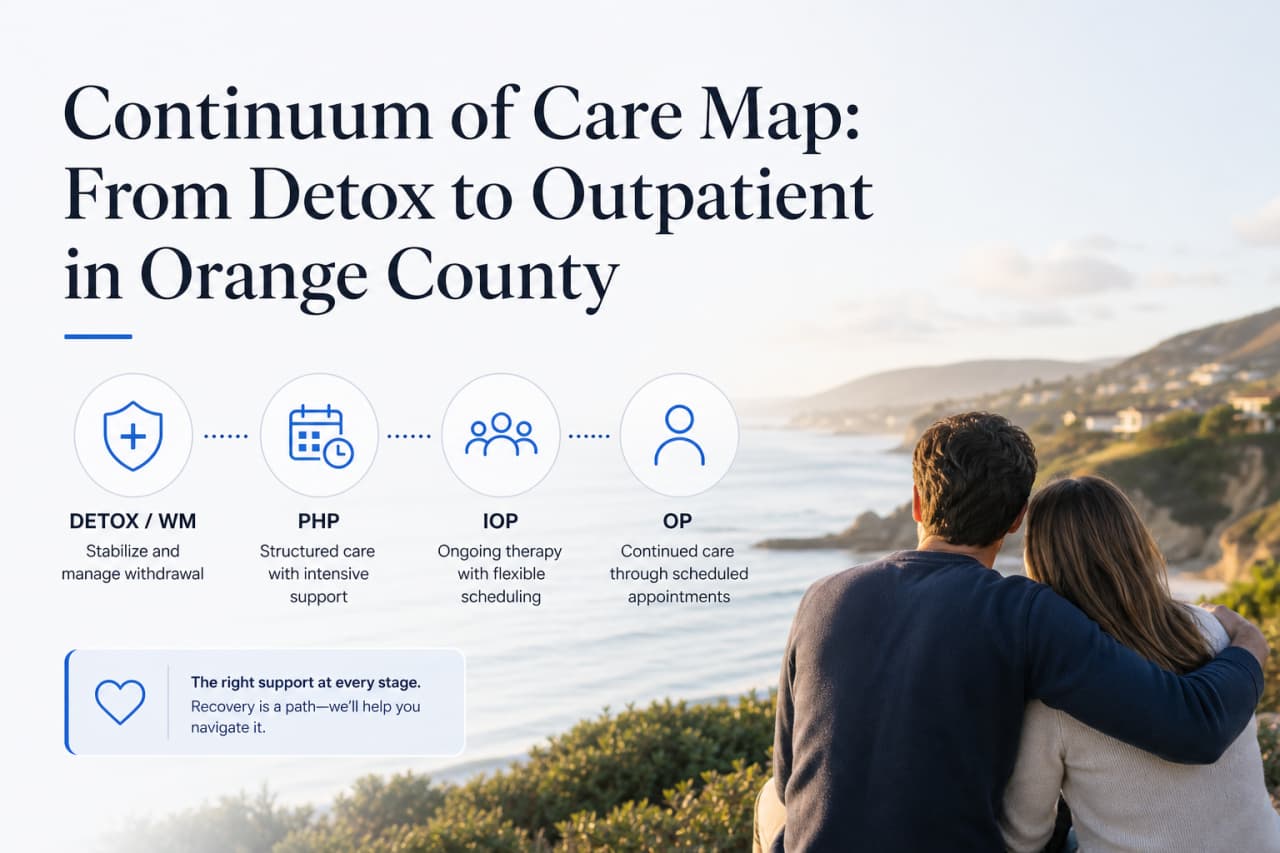
Detox, PHP, IOP, and OP connect in a clear sequence. Here is what each level does and how families can plan safer transitions between programs.
Take the Next Step
If you or a loved one is struggling with addiction or mental health, the Rize OC team is here to help — confidentially and with no obligation.